Accounting
Reports
Trial balance, management accounts, profit and loss and a balance sheet draft.
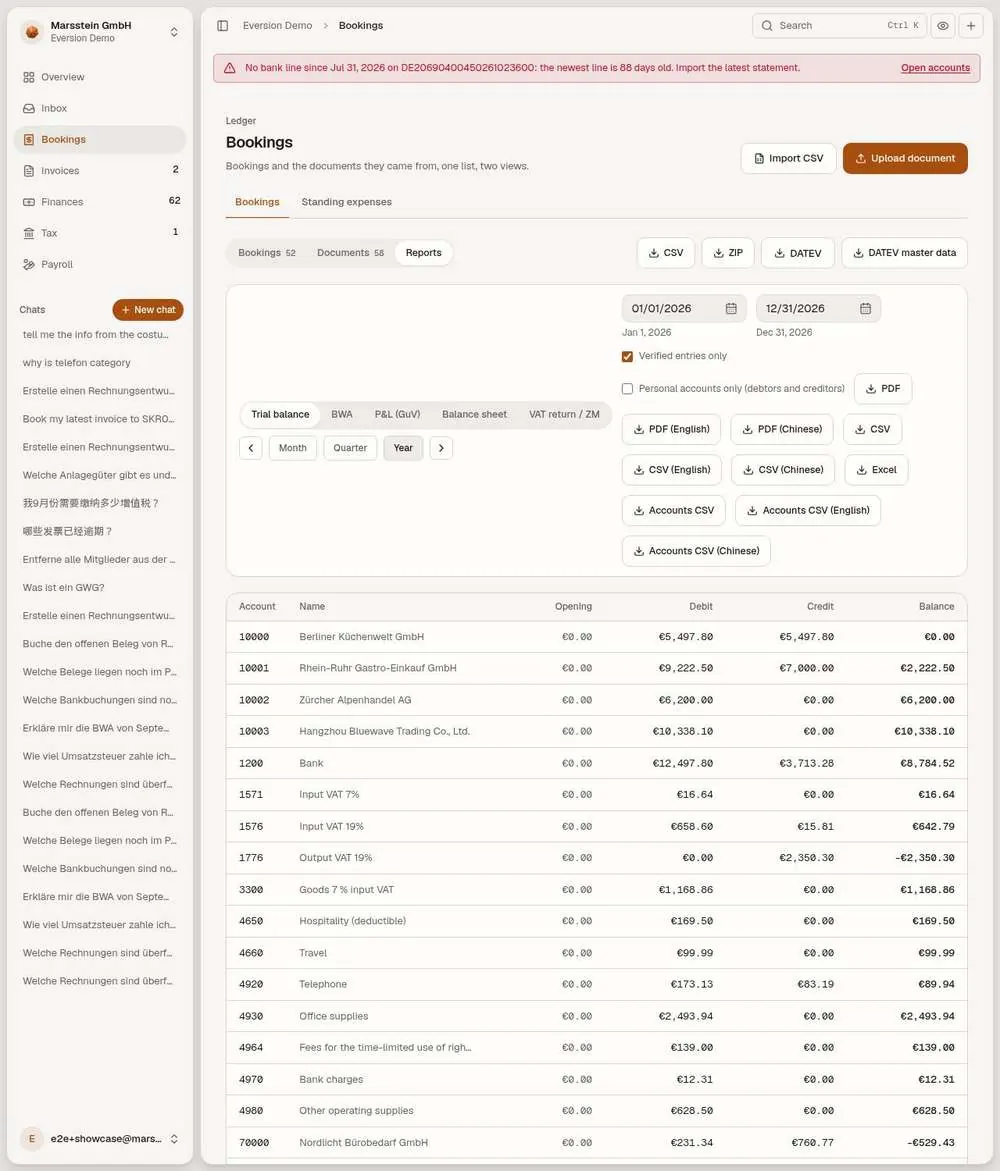
SuSa: trial balance
Account, name, opening, debit, credit and balance per account, period selector (Month, Quarter, Year), 'Verified entries only', a filter for personal accounts, and downloads (PDF, CSV, Excel, Accounts CSV, in English or Chinese).
In short
Try it
Switch the period to Quarter.
Open one account.
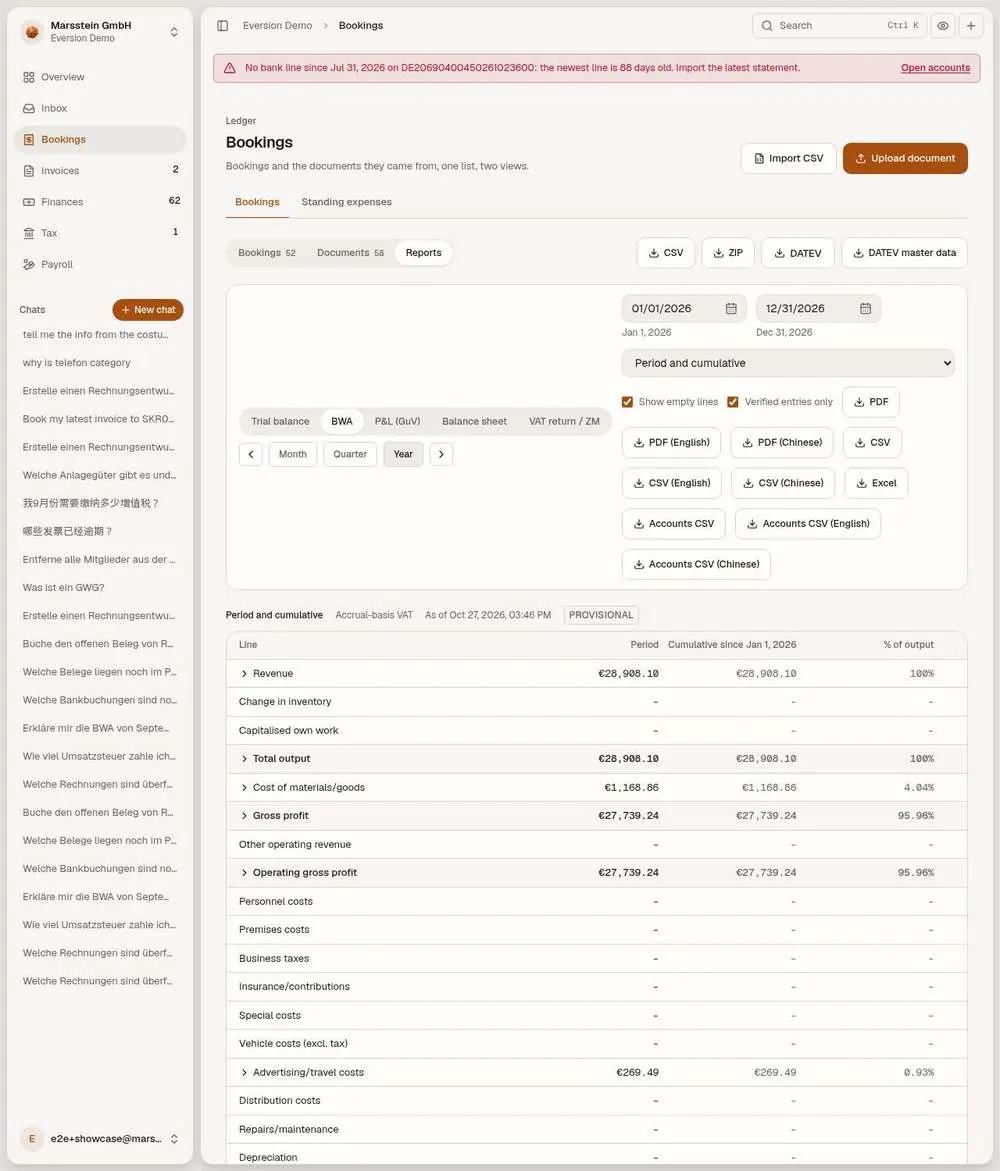
BWA: management accounts
Lines for revenue, change in inventory, capitalized own work, total output and the cost groups, each with percent of output and of costs, a 'Period and cumulative' view selector and the tag PROVISIONAL.
In short
Try it
Open the view selector.
Good to know
- The agent has no BWA tool; use this screen (see Agent limits).
GuV: profit and loss
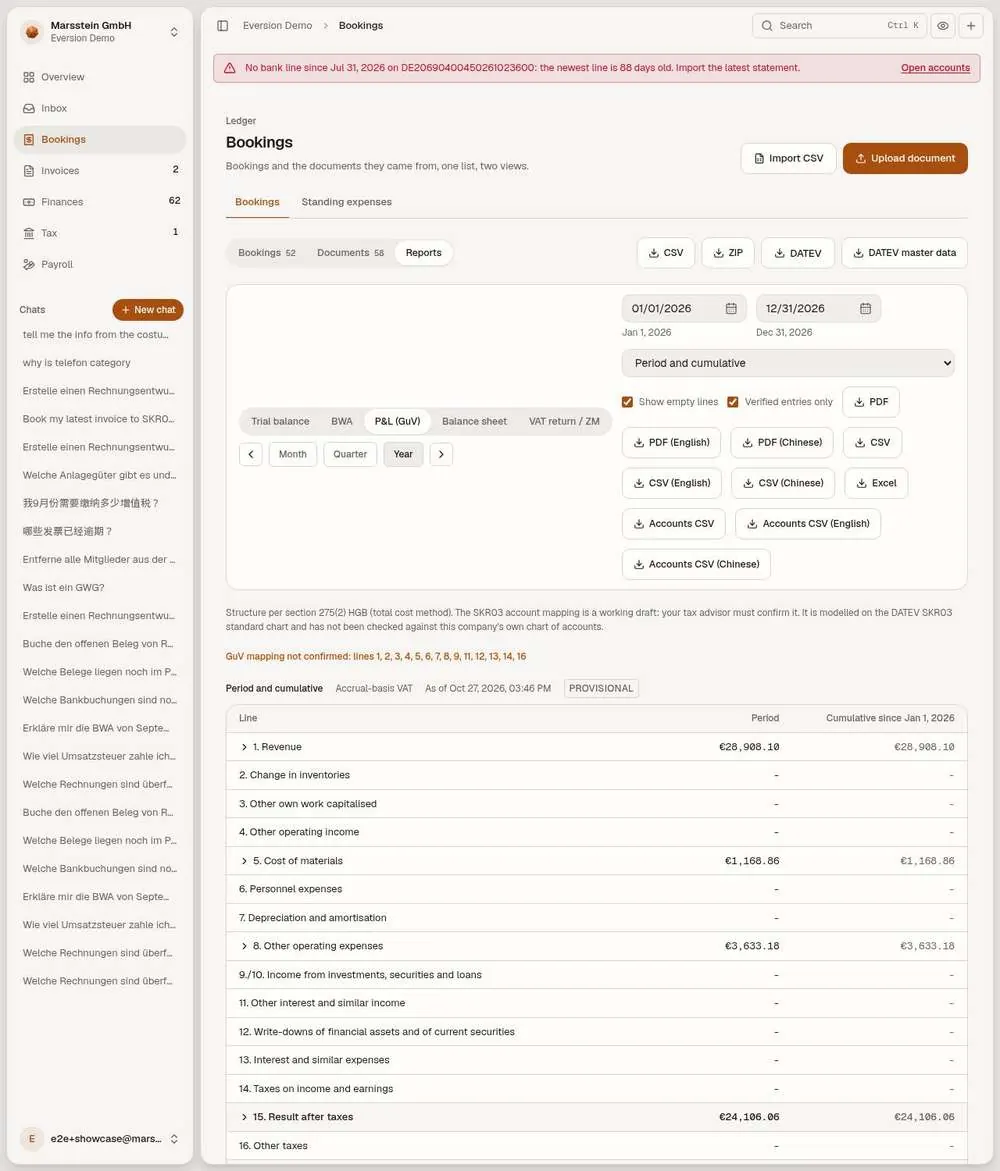
The profit and loss statement in the total cost method (§ 275 Abs. 2 HGB). A note says the SKR03 mapping is a working draft that the tax adviser must confirm, and lists the lines not yet confirmed.
In short
Try it
Compare the result with the BWA.
Good to know
- Mapping unconfirmed, as the screen states.
Bilanz: balance sheet draft
Assets on the left, equity and liabilities on the right, structure per § 266 HGB. A note: 'Draft: your tax adviser prepares the balance sheet in DATEV. The SKR03 account mapping is a working draft'. Lines with unconfirmed mapping are listed.
In short
Try it
Read the draft label.
Good to know
- Draft until the adviser confirms the mapping.